Mortgage Advice You Can Trust

Danielle McIntosh Baggiarini,

Mortgage Expert

GET STARTED
Providing you with the very BEST mortgage options to suit YOUR unique and individual needs. 

Finding the best mortgage can be frustrating. It doesn't have to be when you follow my 3 step plan.

Get started right away

The best place to start is to connect with me directly. My commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise. I'll outline the best mortgage products available with your needs in mind.

Proceed with confidence

My goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, I'm available to answer any questions for as long as you need a mortgage. I've got you covered.
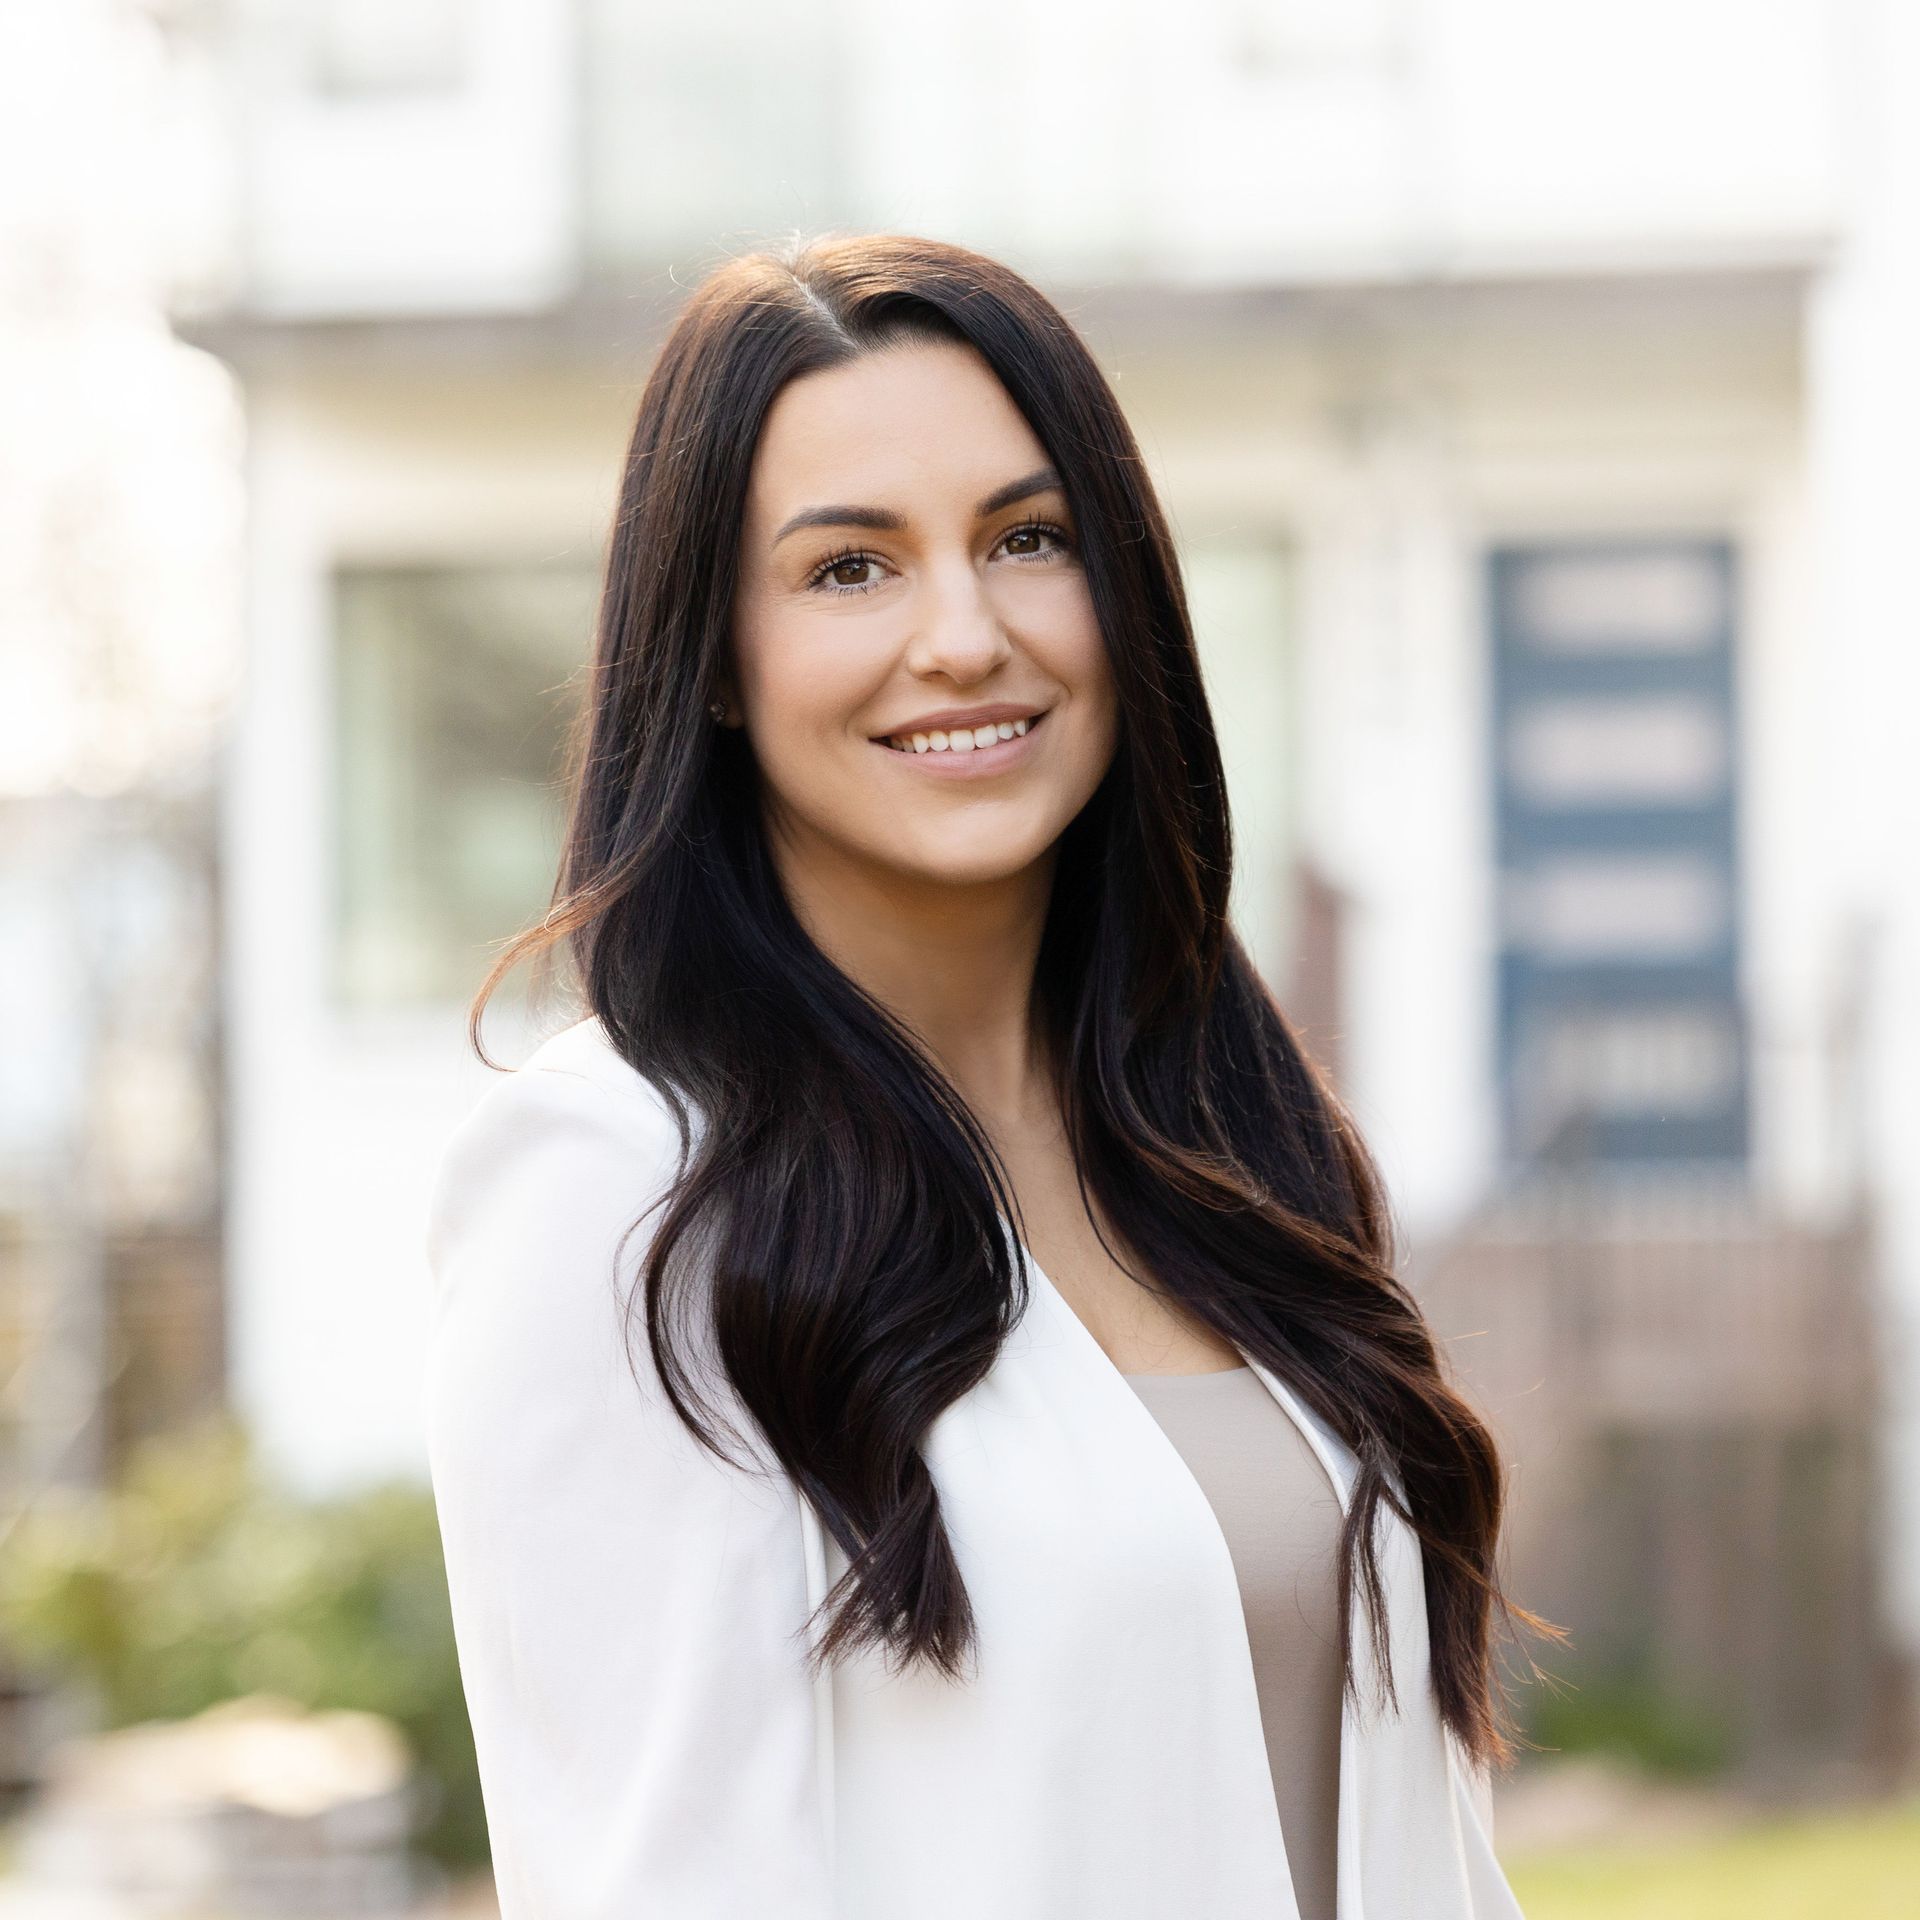
Danielle McIntosh Baggiarini

I am a licensed mortgage broker in BC. My experience and expertise have allowed me to work with a diverse set of clients. I arrange mortgages for couples, singles, or families who are either purchasing their very first home, upsizing, downsizing, or purchasing an investment property / vacation home. I also facilitate refinances to consolidate high interest debt, finance tuition, vacations, contribute to investments, or add a home equity line of credit. I am your advocate helping you get a mortgage that fits your lifestyle and financial goals, I will also be following up with you for the duration of your term to make sure you are happy.


I have been a licensed mortgage broker since 2015, and I’ve learned from some of the best mentors in the industry.

I offer a free, no-obligation consultations where you can ask me your mortgage financing questions. Click Below To Book It.
BOOK FREE CONSULT

Nice things people have said about working with me.

Get started by completing my online mortgage application.

I'll let you know exactly where you stand so you can proceed with confidence.

APPLY NOW

Mortgage articles to keep you informed.

Two people reviewing a document at a kitchen table with a laptop, coffee mug, and mountain view in the background
By Danielle McIntosh • November 4, 2026
Can you switch mortgage lenders without another stress test? Learn how uninsured straight switches work in BC and what lenders still review.
By Danielle McIntosh • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Danielle McIntosh • October 21, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.
Two people reviewing a document at a kitchen table with a laptop, coffee mug, and mountain view in the background
By Danielle McIntosh • November 4, 2026
Can you switch mortgage lenders without another stress test? Learn how uninsured straight switches work in BC and what lenders still review.
By Danielle McIntosh • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Danielle McIntosh • October 21, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.
Show More

Everything you need, all in one place

As a trusted mortgage provider, let me help you with these services.

Go ahead and schedule a meeting with me!